The IDA PILOT Agreement: New York's Most Powerful — and Most Misunderstood — Property Tax Incentive.
By Nicholas T. Terzulli, Partner |
DHC’s Economic Development and Tax Incentives Practice Group helps clients navigate tax incentive programs and economic development benefits from New York City and New York State economic development organizations. Our practice group has secured significant, often multi-million-dollar savings, for a diverse range of commercial and nonprofit clients. Meet our Economic Development and Tax Incentives Team.
NEW YORK ECONOMIC DEVELOPMENT ROUNDUP
Economic Development News & Intelligence 10/27/26
There are billions of dollars in New York tax incentives on the table right now for developers and business owners looking to expand or build, but accessing, applying for, and closing on them takes skilled legal guidance every step of the way. Tishman Speyer’s 99 Hudson Boulevard shows how many moving parts one deal has: the developer is in talks with Sony to anchor the tower and is lining up $1.5 billion in debt and $1.2 billion in equity, yet its roughly $100 million tax break won’t return to the city’s IDA until November 17. Tenants, financing, and a tax package all have to land on the same timeline, which is where project finance, real estate, and government affairs counsel work in lockstep. Upstate, IBM’s $2.5 billion quantum facility in Poughkeepsie cleared local environmental review, but its proposed 30-year PILOT was still being negotiated in late September, with the Spackenkill school district pressing for a bigger share and State Senator Rob Rolison weighing in. Local stakeholders like these call for experienced government relations professionals alongside the attorneys out front. Whether a deal needs financing structured, incentives negotiated, entitlements secured, or the right people at the table in Albany or City Hall, DHC’s economic development, project financing, real estate, zoning and land use, and government affairs teams handle it all under one roof. Reach out if we can help.
BUILDING NEW YORK – DEVELOPMENT IN MOTION
The Crown Jewel of the IDA Incentive Bundle
Over the past several weeks, I have written about two of the three core tax benefits that New York State’s Industrial Development Agencies (“IDAs”) can provide to qualifying businesses and developers: the sales tax exemption and the mortgage recording tax (“MRT”) exemption. Both are meaningful. Both are underutilized. And in the right project, both can generate savings that fundamentally improve a deal’s economics.
But if the sales tax exemption is a strong right hand and the MRT exemption is a powerful left, the Payment in Lieu of Taxes agreement — universally known as a “PILOT” — is the knockout punch.
The PILOT is, without question, the most financially significant benefit in the IDA toolkit. On a substantial real estate project or long-term industrial investment, a well-negotiated PILOT agreement can generate millions of dollars in property tax savings over its term. I have negotiated and closed PILOT agreements that produced 20- and 30-year property tax benefits valued at eight figures. I have seen a single PILOT agreement be the difference between a project that pencils and a project that never breaks ground.
If you are a business owner, developer, or investor considering a capital project in New York State, the PILOT deserves your full attention.
New York’s Property Tax Problem
To appreciate the PILOT, you first need to appreciate the problem it solves.
New York State has some of the highest property taxes in the United States. This is not a matter of debate — it is a consistent and well-documented reality. According to data from the Tax Foundation, New York routinely ranks among the top two or three states in the nation for effective property tax rates. For commercial and industrial properties, the burden is acute. Effective tax rates on commercial real estate in parts of New York City, Nassau County, Westchester County, and other high-cost jurisdictions can reach levels that make new development and business investment extraordinarily difficult to justify on a purely financial basis.
This is precisely why IDAs exist. The legislature recognized decades ago that New York’s property tax burden, left unaddressed, would deter the very investment the state needed to sustain its economy. IDAs were empowered to negotiate PILOT agreements as a targeted, project-specific tool to make that investment viable — without requiring a wholesale change to the broader tax system.
What is a PILOT Agreement?
A PILOT agreement is a contractual arrangement between an IDA and a project operator under which the project operator makes negotiated annual payments to the IDA — in lieu of paying conventional real property taxes — and the IDA distributes those payments to the relevant taxing jurisdictions: typically the municipality, the county, and the school district.
The mechanics flow from the IDA’s ownership structure. When an IDA takes title to or a leasehold interest in a project property, that property is technically owned by a governmental entity and is therefore exempt from real property taxation. Rather than allow the property to sit entirely off the tax rolls — which would harm the taxing jurisdictions that depend on that revenue — the IDA enters into a PILOT agreement that requires the project operator to make annual payments that are typically less than what full assessed taxes would otherwise be. The difference between what the project operator pays under the PILOT and what it would otherwise owe in property taxes represents the benefit.
In practice, PILOT agreements are structured in a variety of ways depending on the IDA, the project, and the negotiations between the parties. The most common structures include:
Fixed PILOTs, in which the annual payment is set at a fixed dollar amount for the duration of the agreement, providing maximum predictability for the project operator and certainty for investors underwriting the deal.
Phased-In PILOTs, in which payments start at a lower amount and increase incrementally over the term of the agreement, often on a schedule that mirrors the project’s anticipated revenue ramp-up or lease-up period.
Percentage-of-Assessment PILOTs, in which annual payments are calculated as a percentage of the property’s assessed value, with that percentage increasing over time — for example, starting at 10% of assessed taxes in year one and escalating to full assessed value by the final year of the agreement. These are among the most common structures used by IDAs across New York.
The term of a PILOT agreement is negotiated, and terms vary widely. Short-term PILOTs may run ten years. More substantial projects — particularly those involving significant capital investment, major job creation, or complex transit-oriented or mixed-use developments — may secure PILOT terms of 20, 25, or even 30 years. During my time as a municipal economic development executive in Nassau County, I helped structure and close PILOT agreements across this spectrum, including a 30-year PILOT for a complex transit-oriented development housing community — a transaction that required careful coordination among the IDA, the municipality, the school district, and the developer over an extended negotiation period.
How the Savings Are Calculated — and Why They Can Be Enormous
The financial impact of a PILOT agreement depends on three variables: the value of the property upon completion, the applicable tax rate, and the structure and term of the PILOT.
Consider a straightforward example. A developer constructs a 200,000 square foot commercial building on Long Island. Upon completion, the building is assessed at $15 million. At a combined effective tax rate of 3% — inclusive of county, town, and school district levies — the annual tax bill on a fully assessed basis would be $450,000 per year. Over a 20-year period, that is $9 million in property taxes, before accounting for any assessment increases over time.
Under a PILOT structured at 20% of assessed taxes in year one, escalating to 100% over 20 years, the project operator’s aggregate PILOT payments over the same period might total $4.5 million — a savings of $4.5 million compared to full taxation, in net present value terms likely even more impactful given that the heaviest savings come in the early years of the project when cash flow is most constrained.
Now scale that scenario to a larger project — a $100 million mixed-use development, a major manufacturing facility, a biomedical research campus — and the numbers become transformative. This is why sophisticated developers and businesses treat the PILOT negotiation as one of the most important financial negotiations associated with their project. The stakes are simply too high to approach it casually.
The Negotiation: Where Experienced Counsel Makes All the Difference
Unlike the sales tax exemption — which is largely binary (you either qualify or you do not) — and the MRT exemption — which flows almost automatically from the IDA’s ownership structure — the PILOT is a negotiated agreement. Every material term is on the table: the starting payment level, the escalation schedule, the term, the base assessment, the recapture provisions, and the treatment of future capital improvements. The outcome of that negotiation has a direct and quantifiable impact on the project’s financial performance over the entire PILOT term.
In my experience, there are several principles that consistently distinguish favorable PILOT outcomes from merely acceptable ones.
Start early. The IDA application process requires time — public hearings, environmental reviews, board approvals — and the PILOT negotiation runs alongside that process. Developers and businesses that engage early have more leverage and more time to advocate for favorable terms. Those who come to the table late are often forced to accept whatever structure the IDA presents.
Know the IDA’s policy framework. Every IDA operates under a uniform tax exemption policy (UTEP) that governs the range of PILOT structures it will consider for different project types. Some IDAs publish detailed guidelines; others are more flexible. Understanding the IDA’s policy posture before negotiations begin allows counsel to tailor the application and the negotiation strategy accordingly. Deviation from a UTEP is permissible, but requires a special notice to all affected taxing jurisdictions.
Understand the taxing jurisdictions. The IDA distributes PILOT payments to the relevant taxing jurisdictions — the municipality, the county, and critically, the school district. School districts in particular often have strong views about PILOT agreements, as property taxes are their primary revenue source. In some IDA processes, school districts have a formal advisory role; in others, they do not. But as a practical matter, a PILOT structure that leaves the school district feeling shortchanged can create friction, public opposition, and reputational risk for the project. A well-advised applicant understands these dynamics and structures the PILOT to be defensible to all stakeholders.
Model the full financial impact. A PILOT agreement is a long-term financial commitment. A sophisticated applicant — and their lender — will model the full PILOT payment schedule against projected property tax obligations under full assessment, discounted to present value, stress-tested against assessment increase scenarios, and integrated into the project’s overall pro forma. Decisions made at the negotiating table should be grounded in that analysis, not just a general desire to minimize payments.
Recapture: Understanding Your Exposure
As with other IDA benefits, PILOT agreements include recapture provisions that allow the IDA to recover benefits if the project operator fails to meet its commitments. In the context of a PILOT, recapture typically means the project operator becomes obligated to pay the full property taxes that would have been due absent the PILOT — retroactively, for the period of non-compliance, plus interest and penalties.
This is not a hypothetical risk. IDAs take their monitoring and compliance obligations seriously, particularly in the current environment where public scrutiny of economic development incentives is heightened. Understanding the recapture provisions of your PILOT agreement — and building realistic commitments into the application — is not just good legal practice. It is essential risk management.
The PILOT in Context: The Full IDA Incentive Bundle
The PILOT does not exist in isolation. As I have written previously, the IDA can simultaneously deliver a sales tax exemption on construction materials and equipment purchases, and an MRT exemption on the project financing. Together, these three benefits — what I refer to as the IDA incentive bundle — can generate a combined financial impact that fundamentally changes the economics of a New York capital project.
A developer undertaking a $50 million mixed-use project on Long Island, for example, might realize: $3 million to $4 million in sales tax savings on construction purchases; $200,000 – $300,000 in MRT savings on the project financing (depending on how much is financed); and $10 million or more in property tax savings over the PILOT term. That is a combined benefit package could be worth $14 million or more — secured through a single IDA application and approval process.
This is the proposition that makes IDA engagement not just worthwhile, but often indispensable for projects of meaningful scale in New York State.
The Bottom Line
New York’s property taxes are high. That is an immutable fact of doing business here, and no amount of advocacy is going to change it overnight. But for businesses and developers willing to engage the IDA process, the PILOT agreement offers a proven, legal, and politically supported mechanism to manage that burden in a way that makes investment viable.
The IDA PILOT is not a loophole. It is an intentional policy tool — one that the New York State legislature created, funded, and has continuously reauthorized because it works. It brings projects to fruition that would otherwise not happen, creates jobs that would otherwise not exist, and generates tax revenue — even at abated levels — from properties that would otherwise sit vacant or underdeveloped.
The businesses and developers that understand this, and act on it, have a meaningful competitive advantage in the New York real estate and capital investment market. The ones that do not are simply paying more than they have to.
—————————————————
Nicholas T. Terzulli is a Partner and Co-Chair of the Economic Development & Tax Incentives practice at Davidoff Hutcher & Citron LLP. He advises businesses, real estate developers, and nonprofit organizations on accessing multi-million-dollar tax incentive packages through IDAs and other New York State economic development programs. He can be reached at ntt@dhclegal.com or 646-428-3270.
This article is intended for informational purposes only and does not constitute legal advice. Please consult with qualified legal counsel regarding your specific circumstances.
Meet the Author
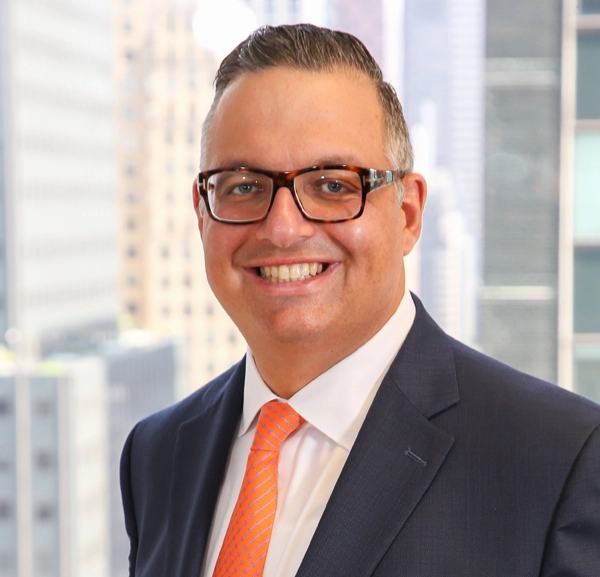
Nicholas T. Terzulli serves as Co-Chair of the firm’s Economic Development & Tax Incentives practice, based in the firm’s New York City office.
Nick’s practice sits at the intersection of business and government, where he advises clients on the legal, policy, regulatory, and strategic dimensions of corporate transactions, real estate matters, economic development initiatives, health care issues, and the cannabis industry.